Newsletter • 5 October 2026

CEE Perspective Weekly Digest- Issue 17

CEE Perspective Weekly Digest- Issue 17

What's on the table this week

Simplification may be the watchword in Brussels, but this week showed that Europe’s financial rulebook is not necessarily becoming less ambitious. ESMA and the EBA set out their priorities for 2027, pairing efforts to reduce regulatory burdens with deeper market integration, stronger supervisory convergence and expanded responsibilities in digital finance. Meanwhile, the ECB turned attention to a different source of change, as the rapid growth of AI investment raises new questions for productivity, financing and financial-market risk.

Across CEE, policy shifts were matched by significant market developments. Romania secured €100 million in EIB financing for one of Europe’s largest planned solar projects, Bulgaria returned to international capital markets with a €2.25 billion bond transaction, and Slovakia recalibrated mortgage rules to distinguish more clearly between first-home buyers and investment purchases. At the same time, rapidly rising house prices in parts of the region and Hungary’s decision to maintain its macroprudential buffers underline the increasingly close relationship between investment growth and financial resilience.

Recent Key EU Developments

1

ESMA puts simpler and more integrated capital markets at the centre of its 2027 agenda

ESMA set out its 2027 work programme on 28 September, placing regulatory simplification, stronger supervision and deeper integration of EU capital markets among its priorities. The programme comes as ESMA assumes a growing role in implementing the Savings and Investments Union and prepares for further responsibilities across digital finance and market supervision. 

Alongside the work programme, ESMA published a dedicated contribution on simplification and burden reduction. The authority is seeking to streamline requirements while preserving investor protection and financial stability, with work spanning reporting, supervisory convergence and implementation of the EU financial rulebook. On 30 September, ESMA also responded to the Commission’s MiCA review, calling for changes to make the framework clearer and better equipped to address emerging crypto-asset services. 

What this means for CEE markets: For smaller financial centres in CEE, the combination of simpler requirements and more consistent EU-wide supervision could lower some barriers to cross-border activity. At the same time, stronger supervisory convergence means firms operating across jurisdictions can expect increasingly consistent application of EU rules. 

EBA’s 2027 priorities combine banking competitiveness with digital resilience

The European Banking Authority published its 2027 Work Programme on 30 September, organised around three themes: improving efficiency, fostering resilience and supporting transformation. Its agenda includes completing implementation of the 2024 banking package, preparing for the new payments framework and advancing work under DORA, MiCA and EMIR. 

The programme also puts greater emphasis on proportionality, integrated reporting and reducing unnecessary compliance burdens, aligning the EBA’s work more closely with the Commission’s banking competitiveness agenda. At the same time, crisis management, deposit insurance, stress testing and supervisory convergence remain core priorities. 

What this means for CEE markets: The emphasis on proportionality and integrated reporting is particularly relevant for banking systems dominated by smaller institutions and subsidiaries of cross-border banking groups. More harmonised supervision and reporting could reduce fragmentation, while the continued focus on resilience reflects the need to preserve strong capital positions amid an uncertain macroeconomic environment. 

ECB links Europe’s AI investment push to productivity, inflation and financial-market risk

At the European Parliament’s ECON Committee on 28 September, ECB President Christine Lagarde set out the ECB’s assessment of the euro-area economy and the growing role of artificial intelligence. The ECB estimates that firms are set to devote around 10% of total investment to AI in 2026, while AI-related borrowing already accounts for roughly a quarter of credit growth to firms. 

Lagarde argued that AI could raise productivity and eventually reduce cost pressures, but stressed that realising these gains will require significant investment in computing capacity, energy infrastructure, skills and innovation. She also highlighted financial-market risks from concentrated valuations and rising debt financing among AI-related companies. Against this backdrop, she reiterated the case for reducing fragmentation in the Single Market and advancing the Savings and Investments Union to improve access to capital for European firms. 

What this means for CEE markets: AI investment could create new demand for digital infrastructure, energy and financing across CEE, but the region’s ability to capture those opportunities will depend partly on access to growth capital and integration into European technology investment flows.
CEE Policy Radar

1

Romania secures €100 million EIB financing for one of Europe’s largest solar projects

The European Investment Bank announced €100 million in financing for Dama Solar on 30 September, supporting a €728 million solar project being developed by Rezolv Energy in Arad County in western Romania. 

With planned capacity of around 1.3 GWp, Dama Solar is expected to become one of Europe’s largest solar power plants. The EIB estimates that it could generate enough electricity for more than 280,000 households, while the project is expected to support more than 1,500 jobs and investment in an EU cohesion region. 

The project is significant not only for Romania’s renewable-energy capacity but also for the wider investment environment. Large-scale energy infrastructure can strengthen energy security while creating demand across construction, grid infrastructure and related supply chains. 

Bulgaria raises €2.25 billion on international capital markets

Bulgaria returned to international capital markets on 29 September, reopening three euro-denominated bond issues and raising a combined €2.25 billion. The transaction added €1 billion to bonds maturing in 2031, €750 million to the September 2034 maturity and €500 million to bonds maturing in 2044. 

Investor orders exceeded €5.5 billion, according to the Bulgarian Ministry of Finance, allowing the government to tighten pricing from initial levels. The financing was issued under Bulgaria’s global medium-term note programme and remains within the government borrowing ceiling established in the 2026 state budget. 

The transaction provides a useful signal of investor appetite for Bulgarian sovereign debt amid continued volatility in European fixed-income markets. It also adds to Bulgaria’s presence in euro-denominated capital markets following its entry into the euro area in 2026. 

Slovakia changes mortgage rules as housing-market risks evolve

Národná banka Slovenska announced changes to its mortgage lending rules on 30 September, introducing a more differentiated approach to loan-to-value limits from January 2027. First-time buyers under 35 will be able to borrow up to 90% of a property’s value, while the standard limit for most borrowers will remain 80%. Financing for the purchase of a third or subsequent property will be capped at 70%. 

The central bank said around one in five mortgages currently goes to borrowers who already own at least two properties. The new framework therefore seeks to ease access to first homes while requiring greater equity contributions for additional property purchases. 

The changes come against a backdrop of renewed housing-market activity. NBS’s latest macroprudential assessment shows that mortgage growth accelerated moderately in the second quarter, while average rates on new mortgages increased from 3.5% in March to 3.9% in August. The central bank nevertheless considers household loan quality favourable and has kept its countercyclical capital buffer at 1.5%. 

Commission steps up pressure on CEE countries over new consumer-credit rules

The European Commission advanced infringement proceedings against Bulgaria, Czechia, Estonia, Croatia, Latvia, Poland, Romania and Slovenia, alongside eight other Member States, for failing to communicate complete transposition of the revised Consumer Credit Directive. The Commission issued reasoned opinions as part of its October infringement package, giving the countries two months to respond and take the necessary measures before the Commission can consider further action. 

The directive modernises EU consumer-credit rules, including requirements relating to information provided to consumers, creditworthiness assessments and protections for borrowers. For CEE financial markets, delays in transposition could prolong differences in the regulatory environment facing banks and other consumer-credit providers across the Single Market. 

Hungary maintains bank capital buffers as property risks remain elevated

The Magyar Nemzeti Bank kept its countercyclical capital buffer at 1% on 30 September and also maintained the 1% sectoral systemic risk buffers covering residential and commercial real-estate exposures. 

The MNB assesses overall cyclical systemic risk as slowly increasing but still at a relatively low, neutral level. However, it highlighted increasing risks associated with housing-market overvaluation and collateral encumbrance, explaining its decision to retain targeted buffers for real-estate exposures. 

The decision illustrates the balancing act facing several CEE central banks: preserving banks’ capacity to lend while responding to renewed property-market pressures and strengthening resilience against a potential reversal in the financial cycle. 

CEE housing markets continue to diverge sharply

New Eurostat data show that residential property prices increased 4.7% year-on-year across the EU in Q2 2026, but several CEE markets recorded considerably stronger increases. Bulgaria registered the EU’s second-highest annual increase at 15.5%, while Lithuania followed at 14.3%.

Quarter-on-quarter movements also underline the divergence within the region. Prices increased 5.0% in Lithuania, 4.5% in Bulgaria and 4.4% in Romania, among the strongest increases in the EU, while Hungary recorded a 1.4% decline. 

For financial markets, the figures matter beyond the property sector. Sustained house-price growth affects household leverage, mortgage demand and bank exposures and is increasingly feeding into macroprudential decisions across the region.

This Week's Events to Watch

1
  • 5–8 October - Council financial-services negotiations: Council experts will continue intensive work in the Working Party on Financial Services and the Banking Union, with meetings scheduled through the week ahead of Friday’s ECOFIN.

  • 6 October - NBS Bank Board: Národná banka Slovenska’s Bank Board is scheduled to meet as the central bank implements its latest macroprudential and mortgage-market decisions.

  • 8 October - Eurogroup: Euro-area finance ministers will meet in Luxembourg ahead of ECOFIN.

  • 8 October - Slovak Financial Market and Innovation 2026: NBS will host its Slovak Financial Market and Innovation 2026 conference, making it a particularly relevant regional event to monitor for financial-sector and digital-finance developments.

  • 9 October – ECOFIN: MISP and banking competitiveness: Finance ministers will be invited to agree the Council’s position on the Market Integration and Supervision Package, a key element of the Savings and Investments Union. Ministers will also exchange views on the Commission’s report on the competitiveness of the EU banking sector, alongside discussions on the Recovery and Resilience Facility, the European Semester, fiscal policy, Ukraine and climate finance.

CEE Perspective Updates

2

The Digital Euro: Perspectives from CEE

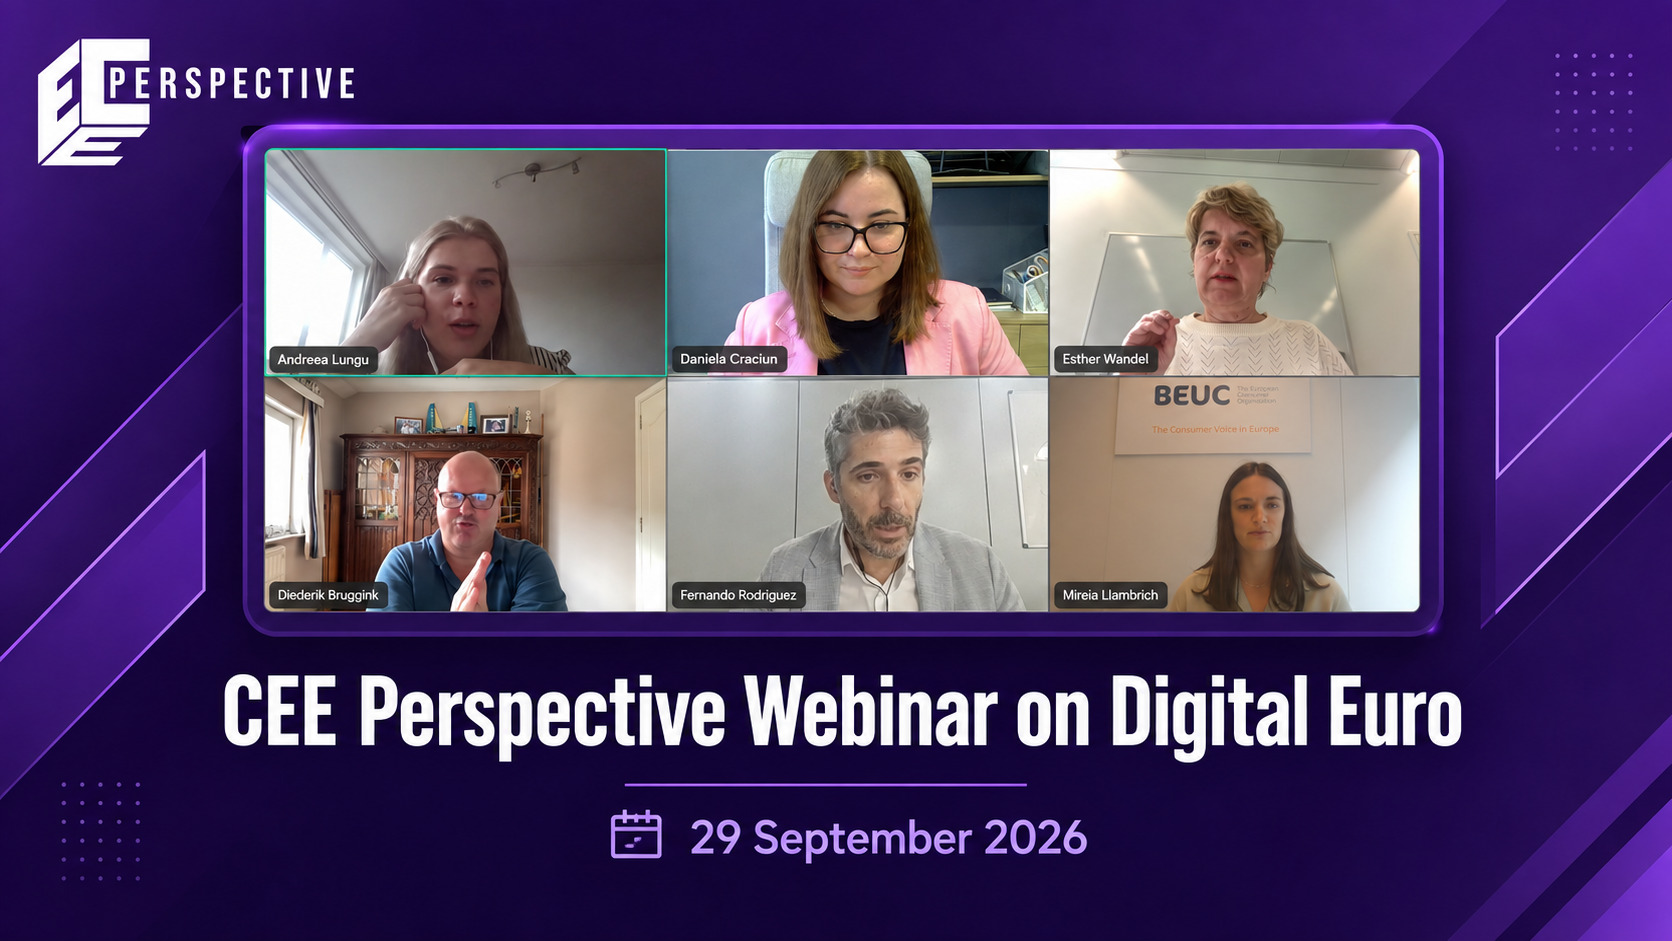
CEE Perspective’s latest Academy webinar brought together central banking, banking industry, payment provider and consumer perspectives on the digital euro and its implications for the CEE region. Dr. Esther Wandel, Diederik Bruggink, Fernando Rodríguez Ferrer and Mireia Llambrich Antó joined a discussion moderated by Andreea Lungu, with questions from the audience.

The webinar concluded our Digital Euro Month, following a series of publications and explainers examining the proposal. We thank our speakers and everyone who joined us, and look forward to returning in October with a new topic and another Academy event.

The recording is available on ourwebsiteandYouTube channel.

The Digital Euro: Perspectives from CEE Watch

The second edition of CEE Market Signal is out!

We followed four developments across the region:

  • Lithuania’s growing household deposits.

  • Estonia’s expanding pension assets, largely invested abroad.

  • Croatia’s widening retail participation in government debt.

  • Czechia’s rising pension pool and the demand for suitable investments.

The common question: how can CEE offer households and pension funds more credible routes into long-term, productive investment?

📖 Read our analysis in CEE Market Signal, Issue 2 below and see all our publications here:https://ceeperspective.eu/publications/cee-market-signal-issue-2

The second edition of CEE Market Signal is out! Watch

Also On Our Radar

1
  • EIOPA identifies extreme heat as an emerging risk for insurers and pension funds: EIOPA published an assessment on 30 September, identifying extreme heat as the most significant climate-related liability risk for life and health insurers and occupational pension providers. Current financial impacts remain limited, but EIOPA expects the materiality of these risks to increase as heatwaves become more frequent and severe.

  • EIOPA sets out its 2027–2029 agenda: The authority published its draft Single Programming Document on 29 September, including its Annual Work Programme for 2027 and setting out planned activities across insurance and occupational pensions supervision for the coming three years.

  • European financing targets electricity-grid investment: The EIB and BNP Paribas announced a €700 million guarantee initiative on 29 September. A €350 million EIB counter-guarantee, matched by BNP Paribas, will support manufacturers of electricity-grid components and investment needed to expand European grid infrastructure.

  • ESMA examines margining in European repo markets: ESMA published a working paper on 29 September examining margining of repo transactions and the allocation of risk between counterparties. The work comes as policymakers pay increasing attention to resilience and liquidity in non-bank and wholesale funding markets.

  • ECB updates its monetary-policy implementation framework: The ECB amended its monetary-policy implementation guidelines on 29 September as part of its regular review of the operational framework through which Eurosystem monetary policy is implemented.

  • European capital-market policymakers focus on public issuance and investor demand: The Commission, EIB and ESM brought together public issuers and institutional investors for their annual Capital Markets Seminar on 30 September–1 October, with discussions covering European public issuance, investment and developments in capital markets.

  • EU unemployment remains broadly stable: Eurostat reported that the EU unemployment rate stood at 6.1% in August, while the euro-area rate remained at 6.4%. Compared with August 2025, unemployment increased by 348,000 people across the EU.

  • Commission challenges Hungary's taxation of government-bond income: As part of its October infringement package, the Commission opened infringement proceedings against Hungary over the tax treatment of income from government bonds, arguing that the national rules may conflict with the EU's free movement of capital. Hungary now has two months to respond to the Commission's letter of formal notice.

  • Commission presses Romania and other Member States over CRD VI transposition: The Commission issued reasoned opinions to Greece, Spain, the Netherlands, Portugal, Romania and Finland for failing to fully transpose the Sixth Capital Requirements Directive. The directive forms part of the EU's implementation of the final Basel III reforms and updates the prudential and supervisory framework applying to banks.